A bicycle accident compensation calculator estimates what a rider hit by a car can recover. It adds up medical bills and lost income, prices pain and suffering with a severity multiplier, trims the total by your share of fault under your state’s rule, and caps the result at the driver’s insurance limit. That is the same arithmetic an adjuster runs. It won’t replace a lawyer and it can’t promise a number, but it shows you the shape of an injury claim before an insurance company frames it for you.
Generic settlement tools shortchange cyclists because a bike case carries three quirks a car case does not. The rider absorbs far more injury per crash, usually holds no insurance on the bike itself, and faces a helmet argument that adjusters like to turn into a weapon. Enter your numbers below and the tool handles all three.
Bicycle Accident Compensation Calculator
Estimate what a cyclist hit by a car can recover, with the three things generic tools miss. Your state's real fault rule, including DC's special protection for riders. The helmet question answered honestly: no state requires adults to wear one, so the insurer's argument is weaker than they let on. And the driver's policy limit, because a state-minimum policy against cyclist injuries is where your own UM/UIM coverage takes over.
Educational estimate, not legal advice. The math follows the standard adjuster framework: economic damages plus a severity multiplier on medical costs, reduced under your state's negligence rule, then capped at the driver's policy limit with the contingency fee applied to the recoverable figure. Published settlement data runs around $233,000 on average with a $45,000 median, a spread that reflects how catastrophic the top of the range gets. State rules reflect mid-2026 law and the DC vulnerable-user statute (D.C. Code 50-2204.52) is modeled conservatively: below its bar, DC may not reduce a rider's damages at all. No state requires adult riders to wear helmets; where the mitigation argument is allowed it reaches head injuries only. Value above the driver's limit is typically pursued through your own uninsured/underinsured motorist coverage, whose availability and stacking rules vary by policy and state. Check your declarations page today, before you need it. Keep the damaged bike and helmet unrepaired as evidence. Statutes of limitations run one to six years by state. Talk to a bicycle accident attorney before accepting any offer; consultations are free and fees are contingent. Seat belt and helmet deductions are injury-only modeling assumptions, not additional collision fault. Whether a defense applies depends on state law, causation, and evidence.
What Is a Bike Accident Claim Worth? Start With the Median
Figures repeated across injury-law firm sites put the mean bicycle settlement near $233,000 and the median near $45,000. None of them trace to a public dataset you can audit, so read them as rough signposts. The gap still tells most of the story. A handful of catastrophic brain and spine cases drag the average settlement far above what a typical rider recovers, so treat any average with suspicion. Your own number is built from your bills, your injuries, and your state, not from someone else’s tragedy.
The tool returns an estimated value of your claim, then splits it into two lines that matter more than the headline: what the driver’s policy can actually pay, and what spills above that limit into your own uninsured/underinsured motorist coverage. It also brackets the result with a conservative end and a strong-case end. No honest estimate is a single point.
In personal injury law, damages are the money awarded for harm, and they come in two kinds. Economic damages (medical expenses, lost wages, and damage to your bike and gear) are the provable floor. Non-economic damages cover the pain, the lost sleep, and the activities you can’t do anymore, and adjusters price them by multiplying medical costs by a factor tied to the severity of your injuries.
| Injury level | Typical bike-crash example | Multiplier in the tool | Range adjusters use |
|---|---|---|---|
| Minor, full recovery | Road rash, bruising, soft-tissue strain | 1.5x | 1.5 to 2x |
| Healed fracture | Collarbone broken in an over-the-bars fall | 2x | 2x |
| Surgical repair | Plates or screws in a collarbone or wrist | 2.5x | 2.5 to 3x |
| Catastrophic | Traumatic brain injury, spinal cord injury, amputation | 5x | 4 to 5x |
Why does severity, not the raw bill, drive a bike case? A rider absorbs what a car’s frame, crumple zones, and airbags would otherwise absorb. The National Highway Traffic Safety Administration classes bicycle riders among vulnerable road users for exactly this reason: the same 30 mph impact that dents a bumper breaks a body. At the catastrophic end, attorneys often commission a life care plan, a medical-economic projection of decades of future care, because the multiplier alone undervalues a permanent disability.
There is one more legitimate argument most tools ignore. Losing the sport itself (the training rides, the club, the commute) is a real quality-of-life loss. It only counts if the record shows it, so tell your treating doctor and write it in a recovery journal.
Using the Bicycle Accident Compensation Calculator Field by Field
Work top to bottom. Every field maps to a lever a real adjuster pulls, so the more honestly you fill it in, the closer the estimate lands.
- Enter your medical bills so far (the one required field): full billed amounts for ambulance, ER, imaging, surgery, road-rash wound care, and physical therapy. Bill everything even where health insurance paid, since liens sort out at settlement and claims are valued on the full bills.
- Add future medical costs you can foresee: hardware removal, scar revision, ongoing therapy, and dental reconstruction, which is common after over-the-bars crashes.
- Pick how badly you were hurt. This dropdown sets the multiplier from the table above, from 1.5x for road rash with full recovery up to 5x for catastrophic brain, spinal cord, or amputation injuries.
- Log your financial losses: lost wages so far (gross pay for all missed time, including burned PTO), future lost earning capacity, bike and gear damage, and other out-of-pocket costs like rides to treatment.
- Choose where the accident happened. This sets your state’s fault rule: a pure or modified fault system, one of the few contributory states, or the District of Columbia’s special protection for riders.
- Enter your share of fault, if any: what the evidence supports, not what the adjuster asserts.
- Answer the helmet question honestly, choosing whether you wore one, whether your state bars the evidence, or whether an insurer is pressing the argument on a head injury.
- Set the driver’s bodily injury coverage, from a typical state-minimum policy ($25,000) up to a 100/300 tier ($300,000), or enter a known limit if you have it.
- Toggle attorney fee and take-home and set a contingency percentage (one-third pre-suit is standard) to see what you keep.
- Click Estimate my compensation. Read the recoverable line and the amount above the driver’s limit together, because that second number is what your own coverage has to carry.
Right Hook, Left Cross, Dooring: Who Is at Fault When a Car Hits a Bike
In most car-versus-bike collisions the driver carries the fault. Legal liability follows the traffic violation, and the three classic bicycle crash patterns usually put that violation on the motorist.
| Crash pattern | What happens | Usual fault on the rider |
|---|---|---|
| Right hook | A driver turns right across the rider’s path | Usually zero percent |
| Left cross | A driver turns left into an oncoming rider | Usually zero percent |
| Dooring | A driver or passenger opens a car door into the bike lane | Usually zero percent; the door opener’s violation almost everywhere |
Adjusters push back anyway. They will argue lane position, missing lights at night, riding against traffic, or a skipped hand signal to move a slice of blame onto you, because every point in your percentage of fault shrinks the payout. Evidence beats argument here: a police report that names the driver’s violation, a statement from an independent witness, and photos of where the bike came to rest. If the driver was drunk or racing, ask a lawyer whether punitive damages are realistic. They are rare, and the estimate does not include them.
State Fault Rules and the Helmet Argument
Comparative negligence is the rule that reduces a plaintiff’s recovery by their own share of fault. Where you crashed decides which version applies, and for a partly blamed rider that can matter as much as the injury itself.
| Fault rule | How it treats a partly at-fault rider |
|---|---|
| Pure comparative fault | Recovery drops by your fault percentage and nothing more |
| Modified comparative negligence (50 or 51 percent bar) | Reduced by your share, then barred entirely once you cross 50 or 51 percent |
| Pure contributory (Alabama, Maryland, North Carolina, Virginia, and DC for drivers) | Any fault at all can bar the claim |
| DC rule for vulnerable road users | The Motor Vehicle Collision Recovery Act (D.C. Code 50-2204.52) lifts the 1-percent bar for riders |
The DC carve-out is the one most riders never hear about. A rider there can recover even when partly at fault, and below the DC threshold the damages may not be reduced at all. The tool models it conservatively. For a plain-English walkthrough of how each system splits blame, see comparative vs contributory negligence.
Does Riding Without a Helmet Cut Your Claim?
Here is what insurers hope you do not know: no US state requires an adult to wear a bicycle helmet. Unlike a seat belt, there is no legal duty to breach, so a bare-headed rider has broken no rule. Several states bar helmet evidence outright, and courts elsewhere frequently exclude it. Where it does survive, it is a mitigation argument confined to head injuries alone, which makes it far smaller and more beatable than an adjuster’s tone implies. A broken wrist or a shattered pelvis has nothing to do with a helmet, and that part of the claim stays untouched.
The Insurance Ceiling: Driver Limits, UM/UIM, and the $25,000 Problem
This is the quiet crisis of bike cases. A rider with serious injuries and six-figure bills is frequently hit by a driver carrying a state-minimum policy, and in many states the bodily injury minimum bottoms out at $25,000, sometimes less than a single night in a trauma unit. What your injury is worth and what you can collect are two separate numbers. You can only collect what there is coverage to pay.
That is why the tool shows the gap above the driver’s limit as its own line. The fix most riders never learn: uninsured and underinsured motorist (UM/UIM) coverage on your own auto policy follows you onto the bike. It covers hit-and-run drivers, it fills the space between the driver’s limit and your losses, and if you own no car, a resident relative’s policy may still cover you. Availability and stacking rules vary by policy and state, so read your declarations page today, long before you need it.
So how much of a $25,000 policy do you actually keep? Say your damages exceed the limit and the driver’s insurer tenders the full $25,000. A 33 percent contingent fee takes $8,250, hospitals and health plans collect on their medical liens, and what remains is the compensation you receive. The recoverable line, not the headline figure, is the honest number, and UM/UIM is where a serious bicycle injury case is often won. Compare the mechanics against a broader car accident settlement calculator or a general accident claim calculator and the same policy-limit ceiling appears every time.
Evidence That Raises a Cyclist’s Settlement
Riders instinctively fix or replace their gear within days, and in doing so they destroy the best physical evidence of impact force they will ever have. A bike crash personal injury case also generates evidence a car crash rarely does. Preserve all of it before you talk to the driver’s insurer.
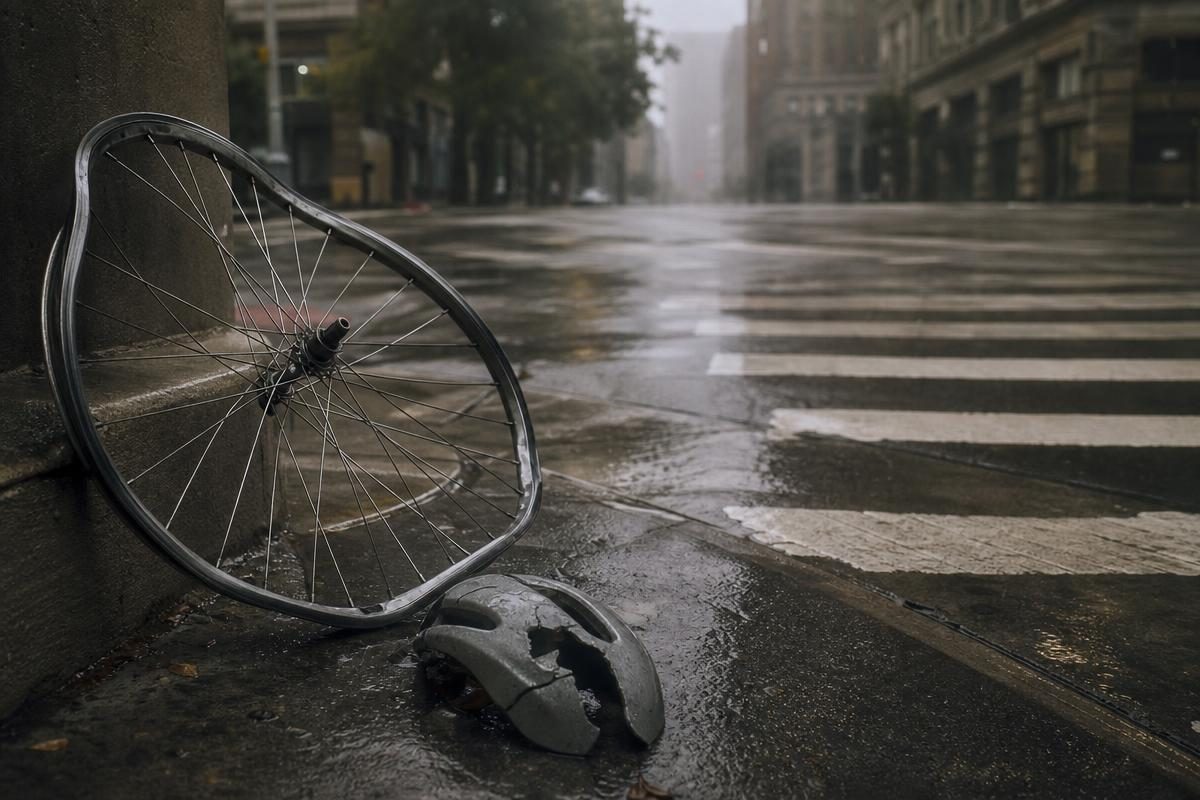
- The bike and helmet, unrepaired. Keep them in a garage corner and photograph everything first. A cracked shell and a bent fork show the force of the hit better than any description.
- Ride data. GPS files from a bike computer or phone app record speed, route, and the moment of impact. They can confirm you were riding lawfully, but they cut both ways if you were moving fast, so let a lawyer see them before an adjuster does.
- Camera footage. Helmet and handlebar cameras loop-record over old files. Save the original clip the same day.
- Medical treatment records with no gaps. A missed month of physical therapy is the first thing an adjuster cites to argue the injury healed.
- A recovery journal. Missed rides, pain levels, sleep, and workdays lost, written down weekly while the details of your injuries are fresh.
For a sense of how documented pain turns into dollars, compare real pain and suffering settlement examples against your own injuries.
Before You Accept a First Offer
Treat every figure here as an educational estimate, not legal advice or insurance advice. Statutes of limitation run anywhere from one to six years by state, and opening offers from insurers are routinely low. A personal injury lawyer reads facts a form cannot: whether the defendant has more than one policy, how the circumstances of the accident will look to a jury, and whether a medical lien can be negotiated down. Most cases settle without a trial, consultations are typically free, and fees are contingent. Riders comparing two-wheeled crash types can also run a motorcycle accident settlement calculator for the overlap.
Start by entering your medical costs and the driver’s policy limit into the bicycle accident compensation calculator above, then pull your own auto declarations page to see what UM/UIM coverage sits behind it. If the estimate lands above the driver’s limit, or anyone is assigning you fault, get the number checked by a lawyer before you sign a release.
Frequently Asked Questions About Bicycle Injury Compensation
How much compensation can I get for a cycling accident?
It depends almost entirely on injury severity, your state’s fault rule, and the available insurance, which is why a range beats any single average. Minor soft-tissue cases often resolve in the low five figures, while surgical and catastrophic injuries reach six and seven figures when coverage exists to pay them. The median figure law firms commonly cite for cyclist cases sits near $45,000, far below the $233,000 mean, though neither number comes from a public dataset.
Who is at fault if a car hits a cyclist?
Usually the driver, especially in right-hook, left-cross, and dooring crashes, where opening a door into traffic or failing to yield is the motorist’s violation. Fault can be shared if the rider was riding without lights at night or against traffic, and recovery then drops by the rider’s share of fault under the state’s rule.
How much of a $25,000 settlement will I actually receive?
After a 33 percent attorney fee of $8,250 and repayment of medical liens, your take-home is the remainder, often roughly half once liens are counted. The take-home line applies the contingency percentage so you see the net rather than the gross, and it flags any value above that limit as UM/UIM territory.
How much will I get from a $50,000 settlement?
A 33 percent fee on $50,000 is $16,500, which leaves $33,500 before medical liens and case costs are repaid. Liens are often negotiable, so the final net depends on how much your health plan or hospital claims and how hard your lawyer pushes back on it.
How is compensation for a bike crash calculated?
Add your economic damages (medical costs, lost pay, and bike and gear damage), apply a severity multiplier to the medical costs to set compensation for pain and suffering, reduce the total by your share of fault, then cap it at the driver’s policy limit. That is the same sequence adjusters and attorneys use to value a personal injury claim.
Will an injury claim calculator guarantee my payout?
No. An injury claim calculator gives a directional estimate and is useful for spotting policy-limit gaps, but no calculator prices a real claim. It cannot read your medical records, judge how a jury sees your injuries, or negotiate. Use the number to prepare and to sanity-check an offer, not as a valuation.
When should I contact a lawyer after a bike crash?
Before you speak to the driver’s insurer or accept a first offer, and certainly before your state’s statute of limitations gets close. Early counsel preserves the wrecked bike as evidence, coordinates any UM/UIM claim against your own insurer, and stops a recorded statement from being used to manufacture fault.